2 min read
What's the biggest payment you make every month? If you're a renter, it's likely your rent.
But even if you pay your rent on time every month, those payments may not appear in your credit history. For renters hoping to buy a home someday, that can be an important consideration when preparing for a mortgage application.
The good news is that credit reporting options are evolving, creating additional opportunities for some renters to have their payment history considered. Here's what you need to know.
The Challenge: Building a Credit History
Having a limited credit history can make qualifying for a mortgage more challenging, even for people who consistently pay their bills.
According to Zillow, insufficient credit history has been identified as a reason some mortgage applicants are denied. Without enough information to evaluate a borrower's credit profile, lenders may have difficulty assessing creditworthiness.
“Nearly one-third of mortgage applicants are denied a loan because of insufficient credit history, making it the most common reason for a denial.”
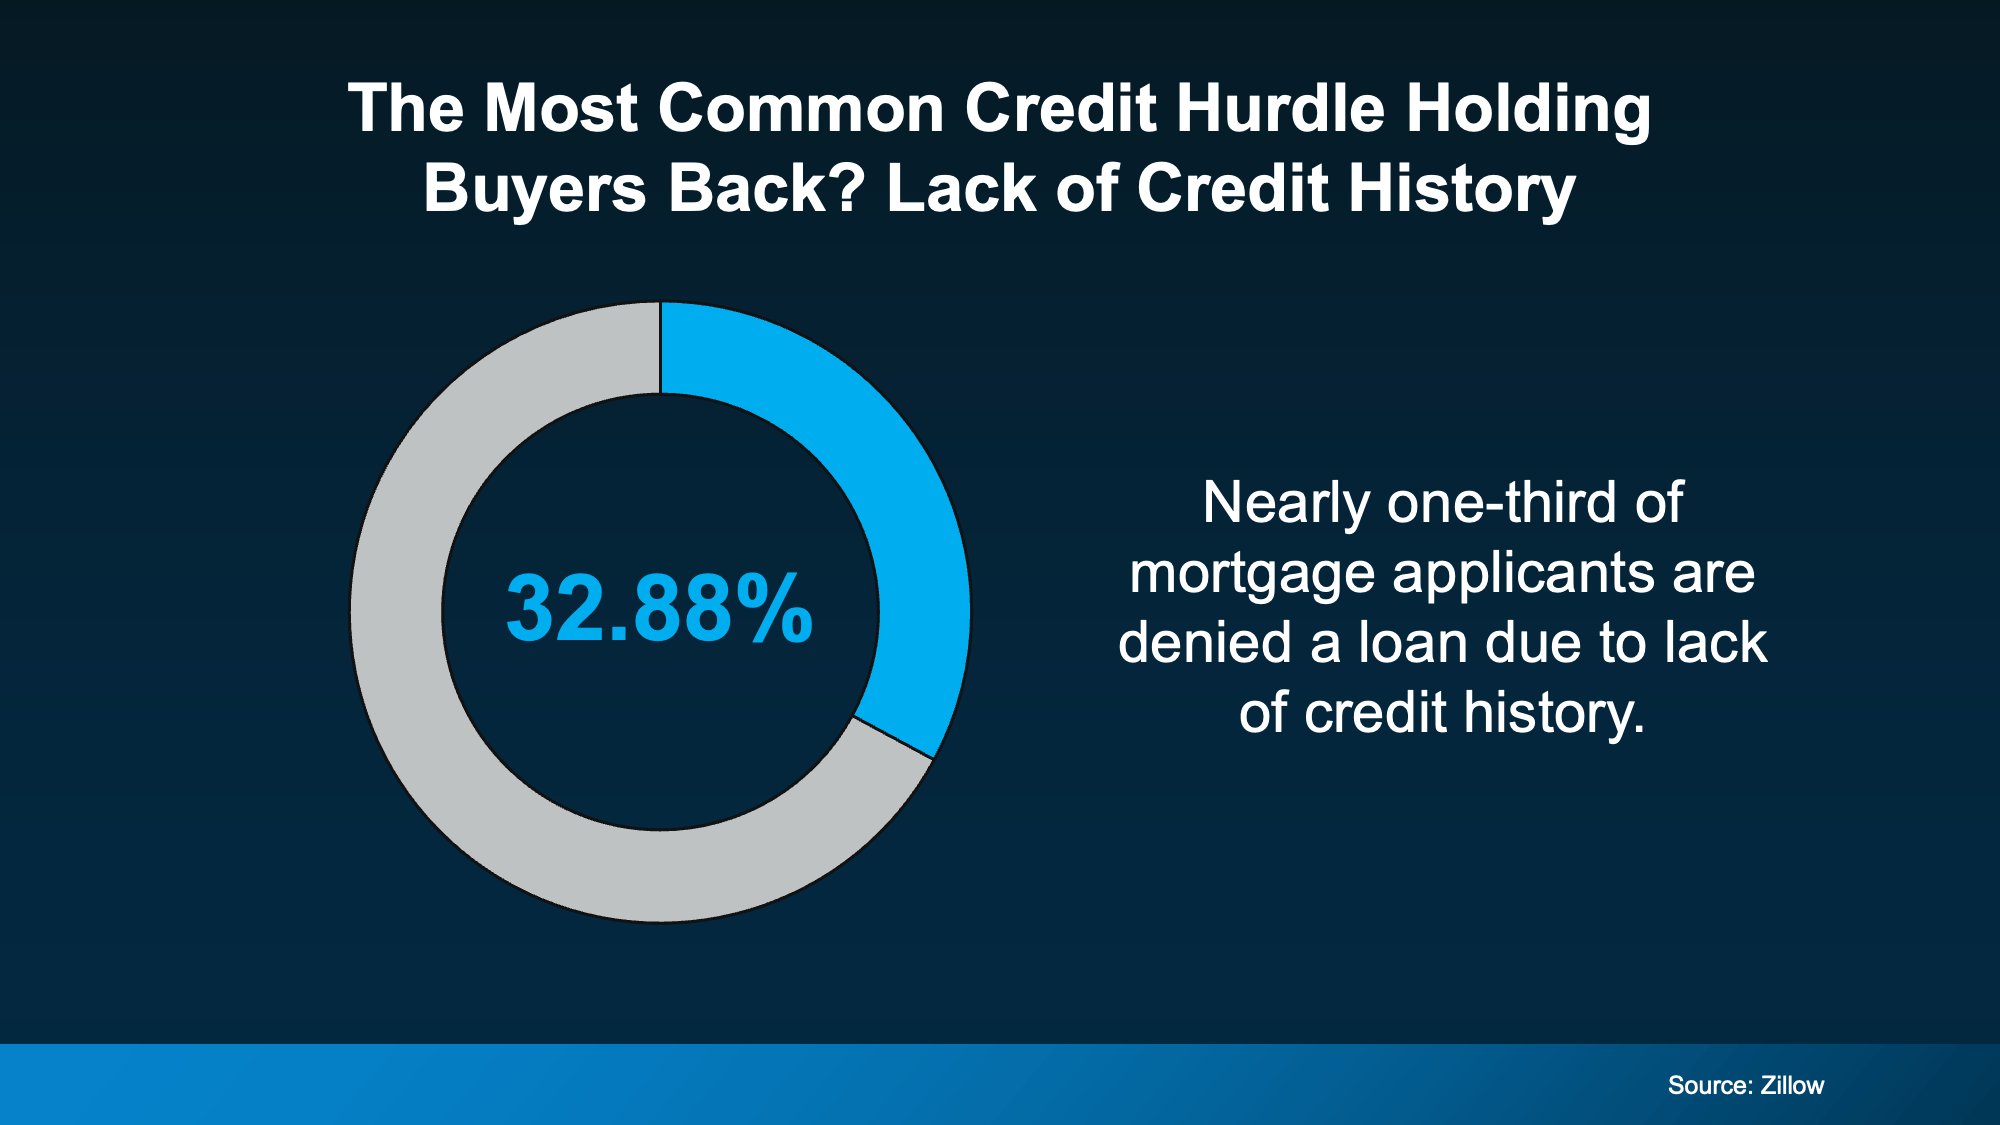
About this statistic: The 32.88% figure reflects the share of mortgage application denials attributed to insufficient credit history, not the percentage of all mortgage applicants who were denied due to insufficient credit history. Source: Zillow Group; Zillow is Helping 78,000 Renters and Counting Turn Monthly Bills into Credit Progress, August 2026
For renters who are working toward homeownership, understanding how credit history is evaluated can be an important first step.
Can Rent Payments Help Build Your Credit History?
Some credit reporting models, such as VantageScore, now consider rental payment history and, in certain cases, utility payments. Research from VantageScore suggests that including positive rental payment data could help some renters become eligible for a mortgage.
However, rent reporting doesn't guarantee a higher credit score or mortgage approval. Results depend on the credit scoring model, lender requirements, and your overall financial profile.
Steps You Can Take Now
If homeownership is a future goal, consider these steps:
- Ask about rent reporting: Check with your landlord or property manager to see whether your on-time payments are reported to credit bureaus.
- Review your credit reports: Look for errors and dispute inaccurate information.
- Build healthy credit habits: Pay bills on time, manage credit card balances, and be thoughtful about applying for new credit.
- Explore your options: Research rent-reporting services and review any fees, terms, eligibility requirements, and cancellation provisions before enrolling.
The Bottom Line
Your rental history may be one part of your financial picture, but lenders consider multiple factors when reviewing a mortgage application.
Even if you're not ready to buy today, understanding your credit and exploring your options can help you prepare for the future.
Have questions about getting ready to buy a home? Connect with a First Federal Bank Loan Officer to discuss your goals and learn about the steps you may want to take toward homeownership.