


2 min read
If you've ever wondered what credit score you need to buy a home, you're not alone. It's one of the most common questions prospective buyers ask. And with changes happening in the mortgage industry, understanding how credit scores work is becoming even more important.
For years, many consumers have assumed they need a credit score of 700 or higher to qualify for a mortgage. But depending on the loan program, a borrower's overall financial picture, and other qualifying factors, the minimum score requirements may be lower than expected.
1. You May Be Overestimating the Credit Score You Need
Many prospective buyers assume their credit score isn't high enough to purchase a home. In fact, recent survey from Veterans United; Credit Rate and Down Payment Myths, has found that consumers frequently overestimate the minimum credit score needed to qualify for a mortgage.
For certain conventional loans, a 620 credit score has historically been a common benchmark1. However, credit score requirements vary by loan program, lender guidelines, and other factors. Some mortgage programs may offer additional flexibility.
A recent survey from Veterans United found consumers continue to overestimate what it takes to qualify for a home loan:
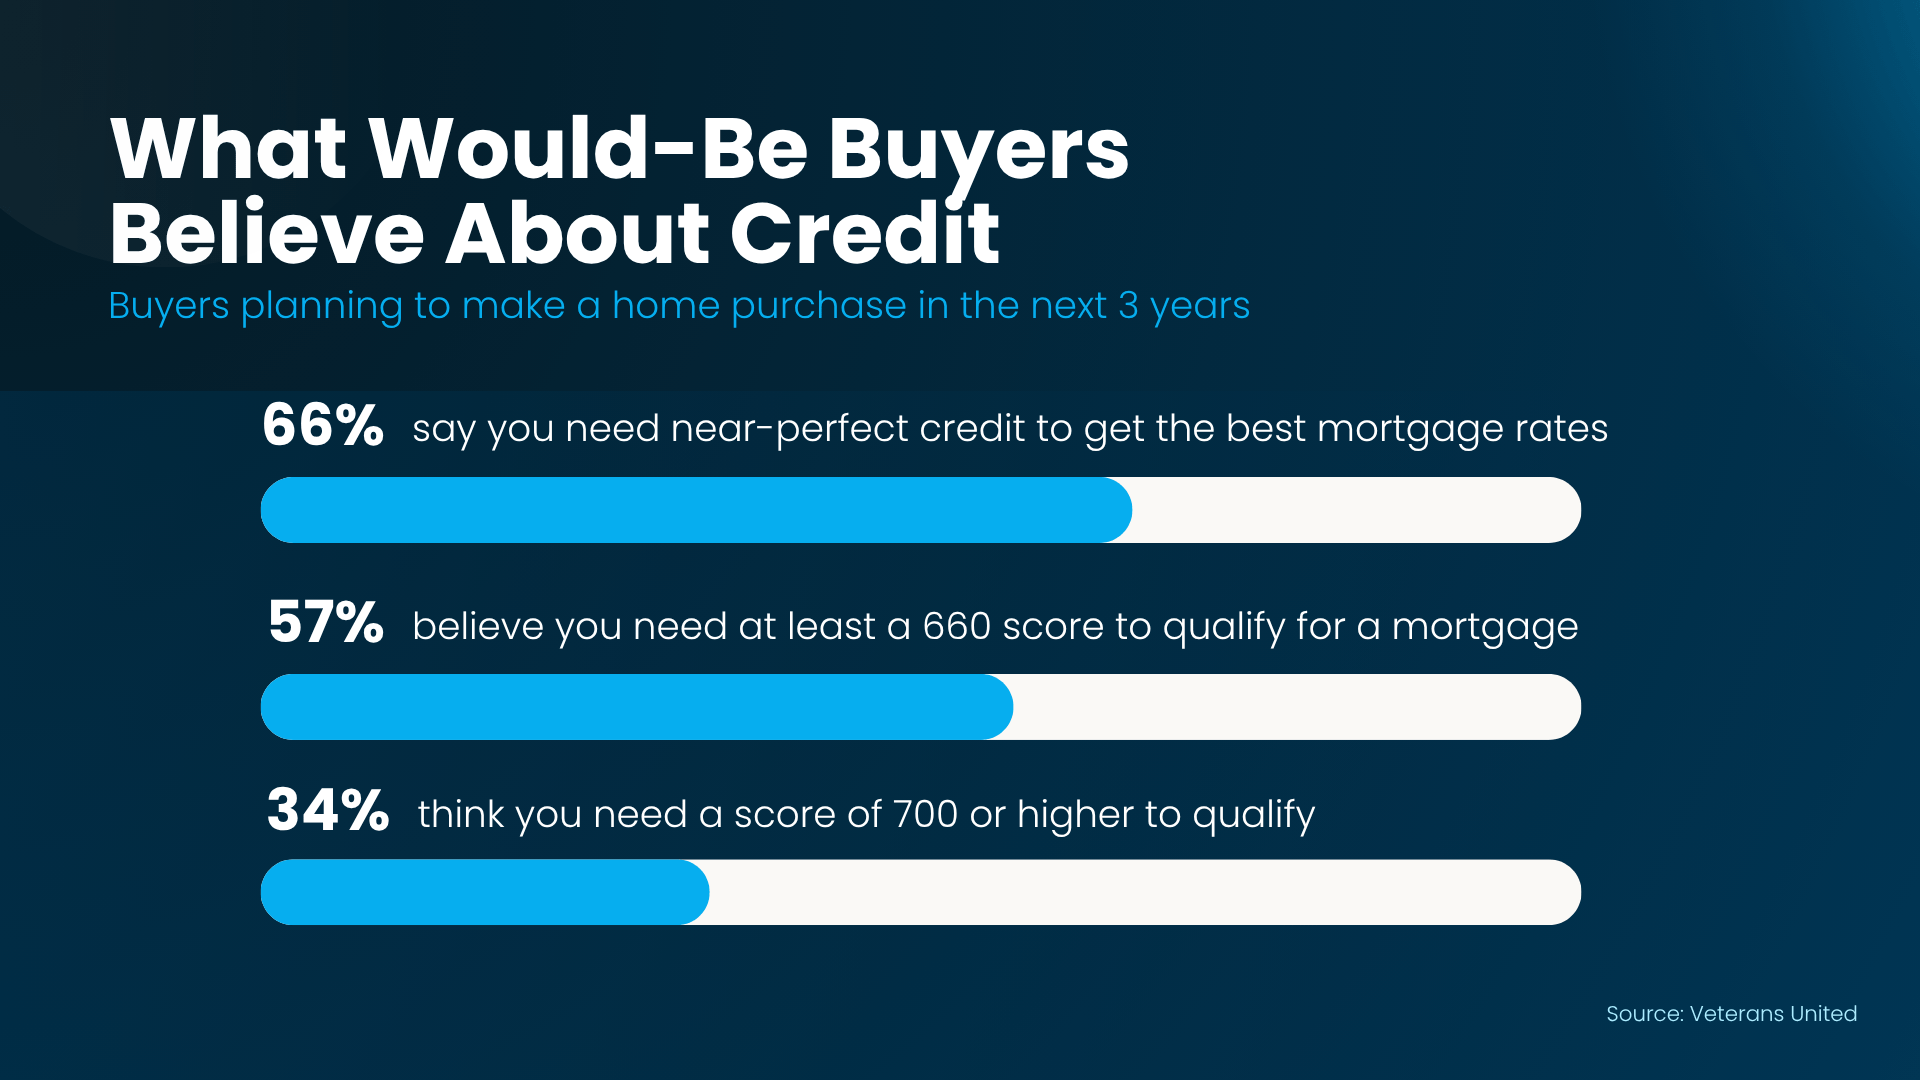
Source: Veterans United, Homebuying 101: Mortgage Myths May Be Holding Buyers Back as Market Begins to Shift in Their Favor, May 2026.
2. Credit Scoring Models Are Evolving
The mortgage industry has traditionally relied on Classic FICO credit scoring models. However, that is beginning to change.
The Federal Housing Finance Agency (FHFA) has approved FICO 10T and VantageScore 4.0 for use by Fannie Mae and Freddie Mac. As part of this publication, approved lenders may use VantageScore 4.0 for eligible loans delivered to the Enterprises, while FICO 10T is not yet eligible for loan delivery.
Why does this matter?
Different scoring models can evaluate credit information differently, which means the same borrower may receive different scores depending on the model used.
Newer models may also evaluate additional or differently weighted credit information, including trends in balances and payment behavior over time, which can produce a different view of a consumer's credit history.
As the industry transitions, it's important to understand that the credit score displayed by a consumer credit monitoring app may not match the score used during the mortgage application process, because lenders may use a different credit scoring model or information from a different credit reporting source.
3. Take Steps to Understand and Manage Your Credit
While credit scoring models may evolve, responsible credit habits remain important. If purchasing a home is on your radar, consider these general credit management practices:
- Pay bills on time: Payment history is an important factor in many credit scoring models.
- Monitor credit card balances: Credit utilization can influence your credit profile.
- Avoid unnecessary new credit: Opening multiple accounts in a short period may affect your credit.
- Review your credit reports: Check for errors or unfamiliar accounts that may need attention.
- Be mindful of major financial changes: Before opening new accounts, closing credit cards, or making significant financial moves, consider discussing the potential impact with your mortgage professional.
Taking time to understand your credit before beginning the homebuying process can help you plan ahead.
Don't Let Credit Score Misconceptions Hold You Back
Credit scoring is changing, and what you think you need to qualify for a mortgage may not tell the whole story.
Every buyer's financial situation is different, and credit score requirements depend on the mortgage program and applicable lending guidelines. The best way to understand your options is to speak with a mortgage professional who can review your circumstances and explain potential next steps.
At First Federal Bank, we're here to help you better understand the mortgage process, answer your questions, and explore financing options that may align with your homeownership goals.
Thinking about buying a home? Start a conversation with a First Federal Bank Loan Officer about your credit, your goals, and what your next steps might look like.
1. Fannie Mae removed its 620 minimum credit score requirement for new Desktop Underwriter® casefiles created on or after November 16, 2025. Credit score requirements may still vary by loan program, lender and investor requirements, underwriting method, and other qualifying factors. See Fannie Mae, Desktop Underwriter/Desktop Originator Release Notes, DU Version 12.0 November Update, updated November 5, 2025. Source: Fannie Mae, Desktop Underwriter/Desktop Originator Release Notes, DU Version 12.0 November Update, updated November 5, 2025.