3 min read
Wondering if now is the right time to buy a home?
Learn about homeownership, home equity, and the factors to consider when deciding whether buying fits your financial goals.
With rising everyday expenses, mortgage rates that may be higher than buyers prefer, and ongoing economic uncertainty, it’s understandable to wonder whether buying a home right now is the right decision.
Purchasing a home is a significant financial commitment, and there is no way to know exactly how the housing market will change.
In the cited survey, most recent homebuyers said they were glad they purchased their current home.
A recent NerdWallet survey found that 74% of recent homebuyers were glad they purchased their current home, while only 3% said they regretted their decision:
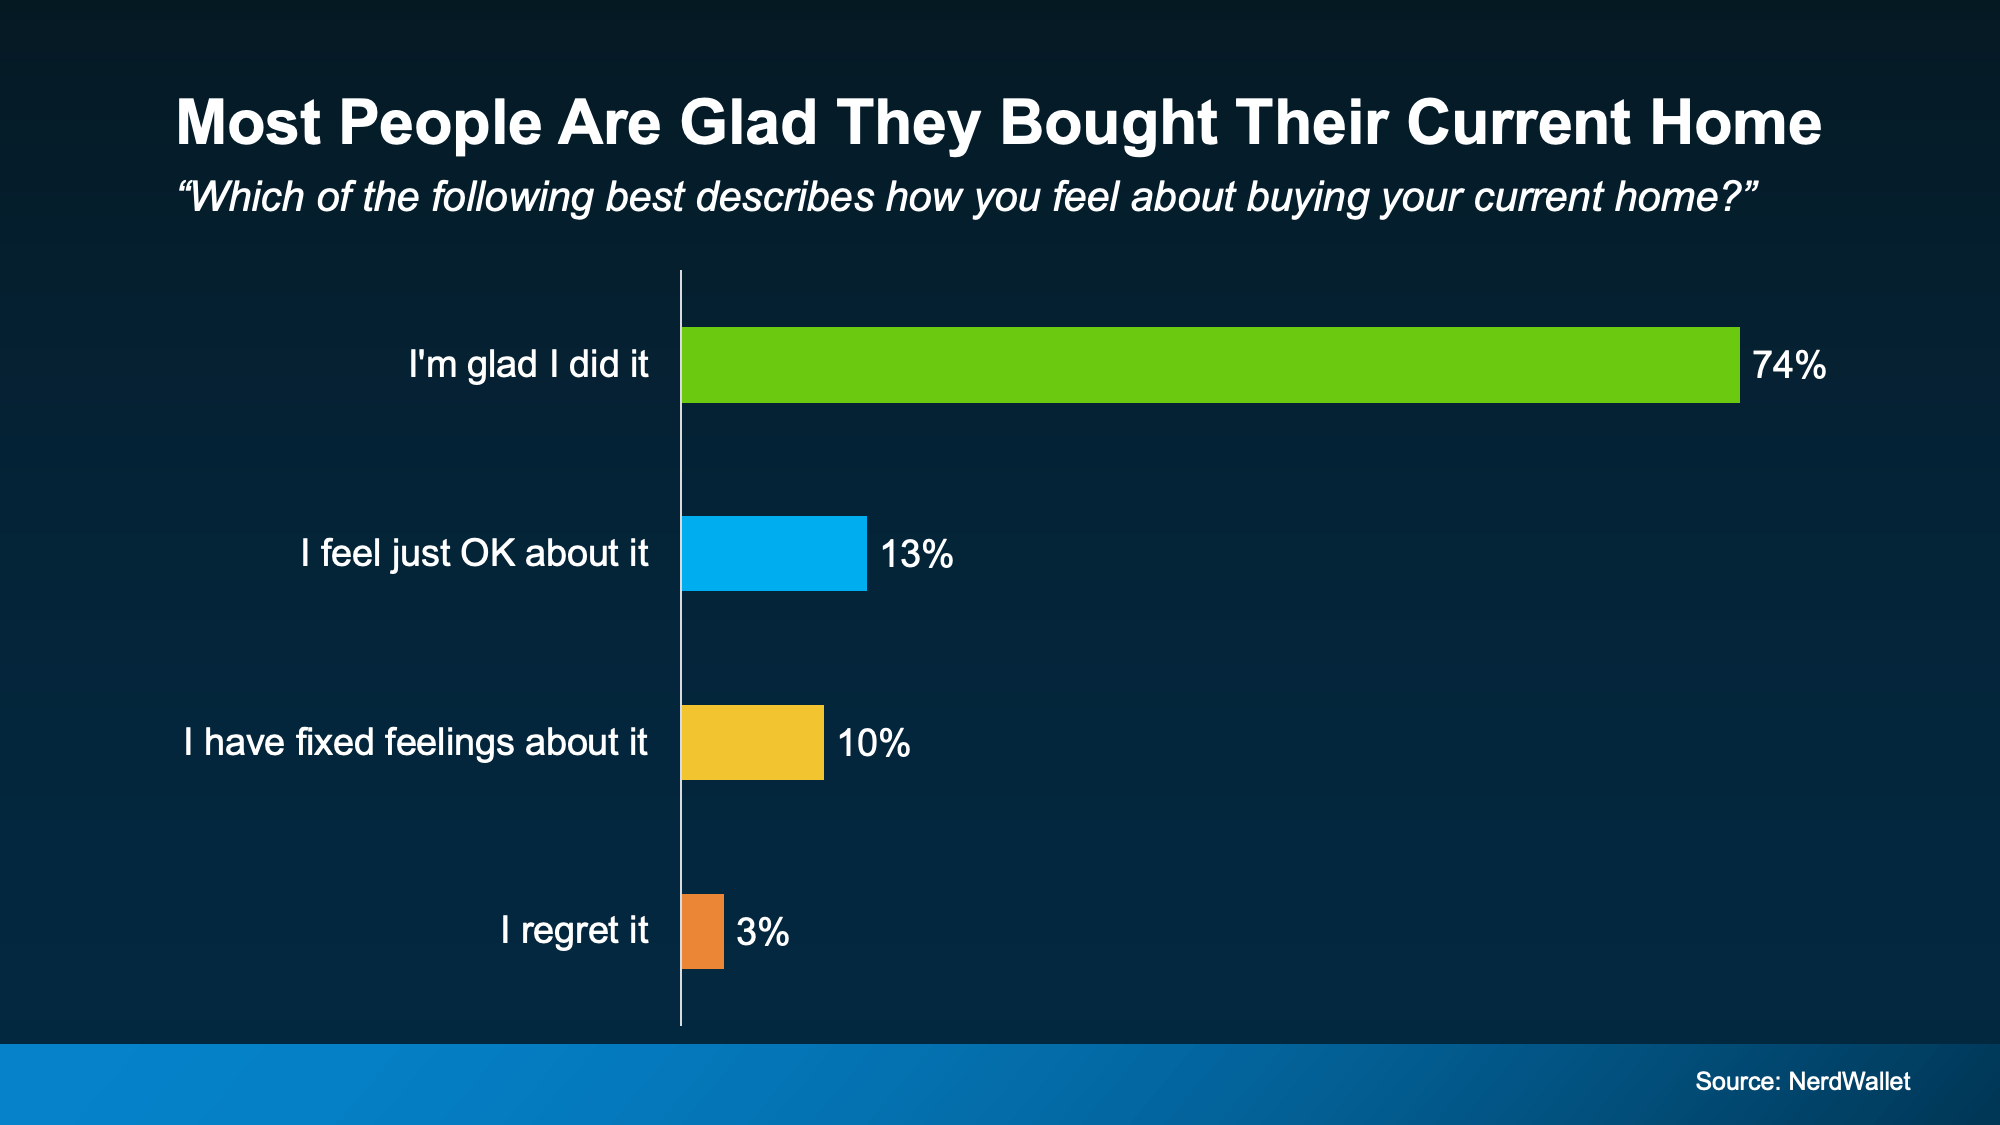
Source: NerdWallet, The Stress of Buying a Home in 2026: How Recent Buyers Responded and What They Already Regret, September 2026. Data reflects national market trends and may not represent conditions in every local market.
Every buyer’s experience is different, but these findings highlight an important consideration: homeownership is about more than trying to purchase at the perfect time. It’s also about evaluating your financial situation, personal priorities, and long-term plans.
Homeownership Is a Long-Term Consideration
When deciding whether to buy a home, it’s natural to focus on current mortgage rates, home prices, and monthly payments. These factors play an important role in determining what fits your budget.
It can also be helpful to consider your longer-term housing needs and financial goals. How long do you plan to stay in the home? Are you comfortable with the costs of ownership? Does purchasing align with your current financial priorities?
Taking time to answer these questions can help you evaluate whether homeownership is an appropriate next step.
Understanding Home Prices and Equity
Historical housing data provides context for how home values have changed over time. According to the Federal Housing Finance Agency (FHFA), national home prices have increased significantly over the past several decades.
(see map below):
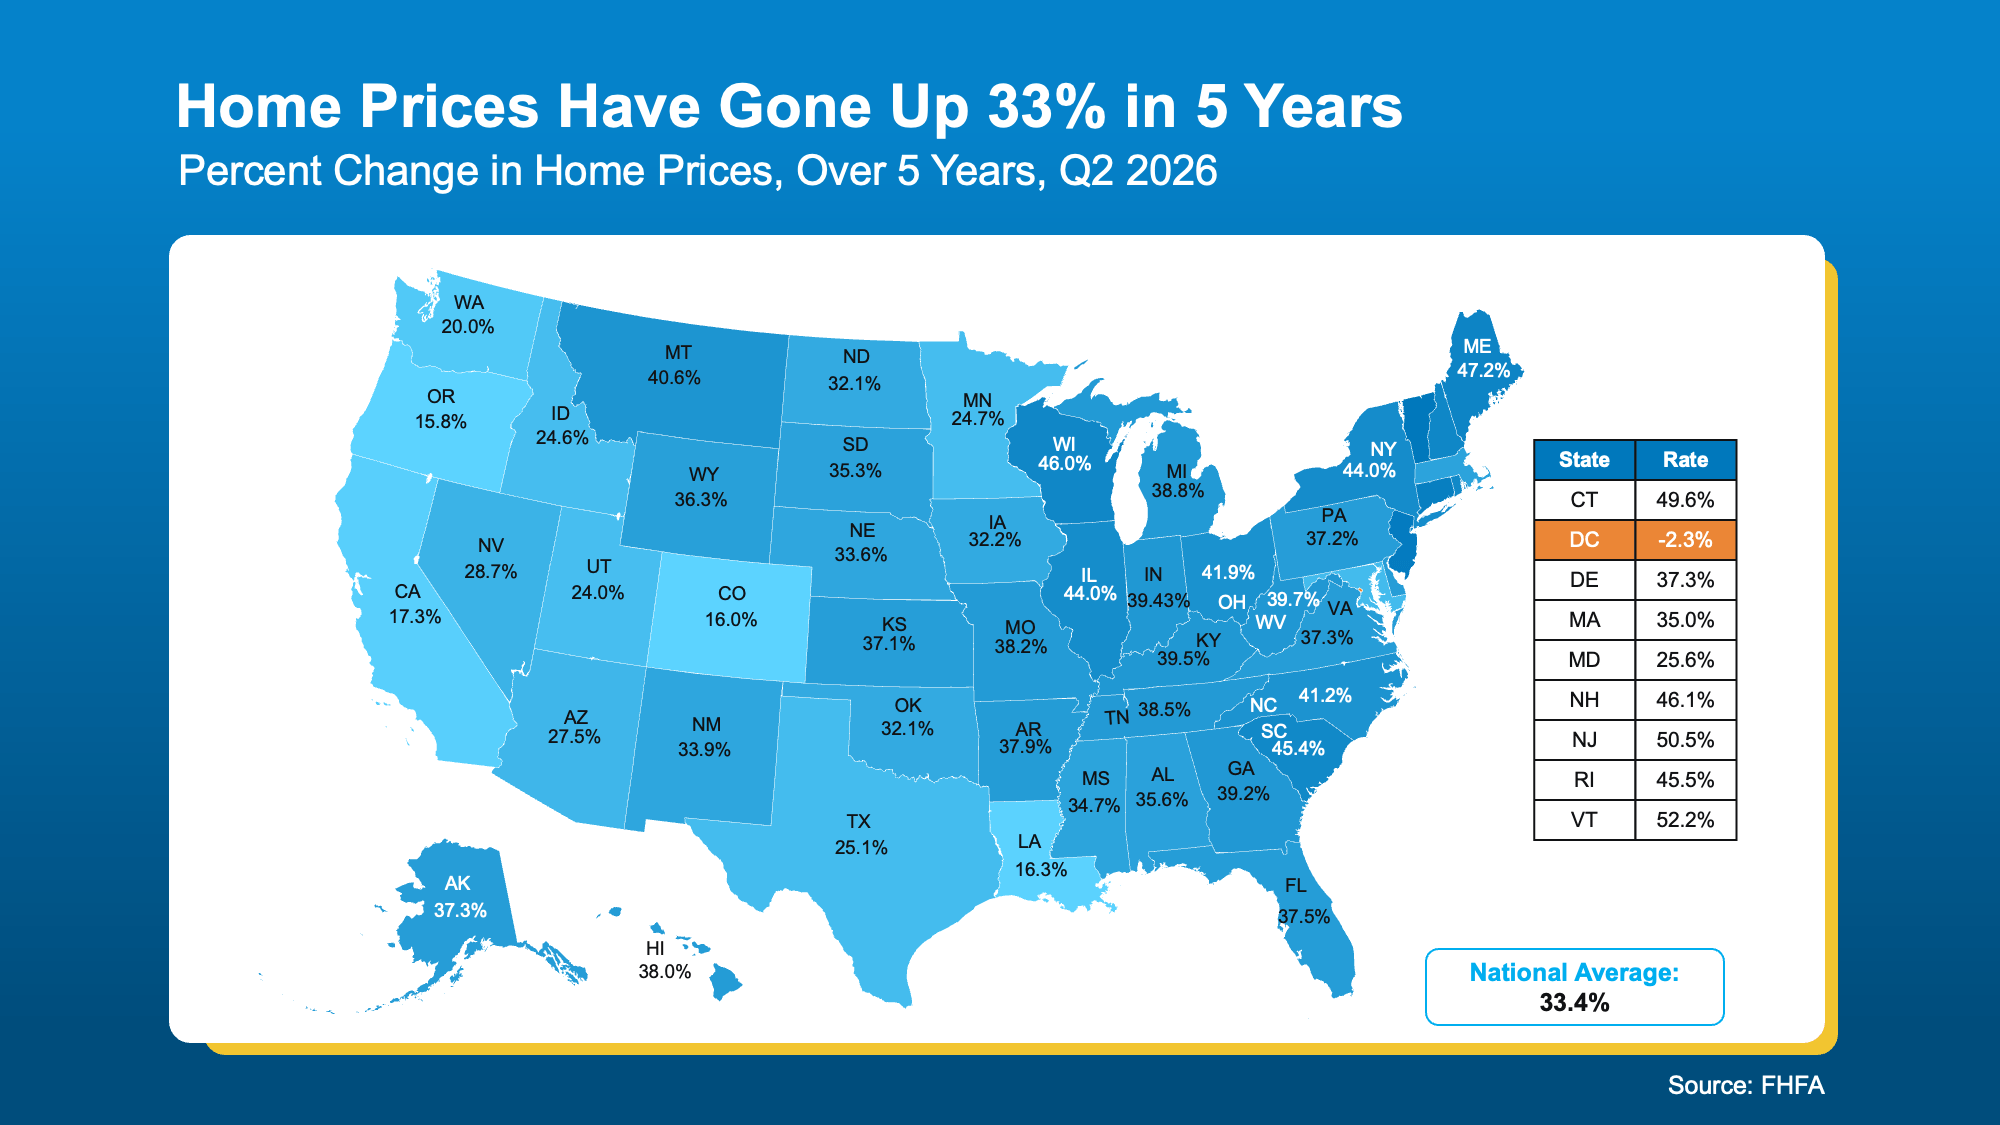
Source: Federal Housing Finance Agency, FHFA House Price Index Datasets, September 2026. Data reflects national market trends and may not represent conditions in every local market.
However, home prices do not increase every year, and appreciation varies by location and market conditions. Past performance does not guarantee future results.
One aspect of homeownership to understand is home equity, which is the difference between a property's current market value and the outstanding mortgage balance.
Equity may change as you pay down your mortgage principal or as your home's market value fluctuates. The amount of equity you accumulate depends on factors such as your loan terms, payment history, and changes in the housing market.
If you eventually sell your home, any remaining equity may contribute to your net proceeds after the mortgage balance and applicable selling expenses are paid. Some homeowners may use those proceeds toward another property or other financial goals.
However, equity is not guaranteed to grow, and accessing it through a loan or line of credit involves additional costs and repayment obligations.
Look Beyond Today's Housing Market
Trying to predict the perfect time to buy can be challenging. Mortgage rates, home prices, and available inventory can change, making it difficult to know how today's conditions will compare with those in the future.
Rather than relying on market predictions alone, consider what purchasing a home would mean for your finances today.
Before moving forward, consider:
- Your monthly budget: Account for the mortgage payment, property taxes, homeowners insurance, maintenance, and other homeownership expenses.
- Your savings: Consider whether you have funds available for upfront costs and unexpected expenses.
- Your plans: Think about how long you expect to stay in the home and whether the property meets your needs.
- Your financing options: Explore available mortgage programs and compare the terms, costs, and requirements.
Buying a home may make sense for some households, while renting may be more appropriate for others. The right decision depends on individual circumstances, not simply on where the housing market stands today.
How First Federal Bank Can Help
At First Federal Bank, we understand that buying a home can bring both excitement and questions. Understanding your financing options and the costs involved can help you make a more informed decision.
Our Mortgage Loan Officers can discuss your homeownership goals, explain available loan options, and help you understand the factors that may affect your purchasing budget. While no one can predict future market conditions, having a clear picture of your options can help you determine what may work for your situation.
Thinking about buying a home? Reach out to a First Federal Bank Loan Officer to start a conversation about your goals and explore your options.